There is a moment I remember clearly. It was a Tuesday evening, and I was sitting at the kitchen table with a pile of receipts and a calculator, doing the same math I had done a hundred times before. The number never worked. My income had gone up twice in three years, yet somehow the gap between what I earned and what I kept stayed exactly the same.
That is when I started reading books about money management. Not to get rich. I just wanted to understand why working harder was not working.
Most money books tell you to budget, cut coffee, and wait. That advice never touched the real problem. The real problem was how I thought about money, not how much of it passed through my hands.
Quick Answer: What do good money management books actually change?
They change how you see money. Not as a monthly event, but as a system. The best ones teach you to pay yourself first, tell assets from liabilities, and let time do the heavy lifting.
Why Does More Income Never Feel Like Enough?
I used to believe the answer was simple. Earn more. Then I watched a colleague get a significant raise and immediately buy a car he did not need. Six months later, he was stressed about payments. Nothing had changed except the size of the numbers.
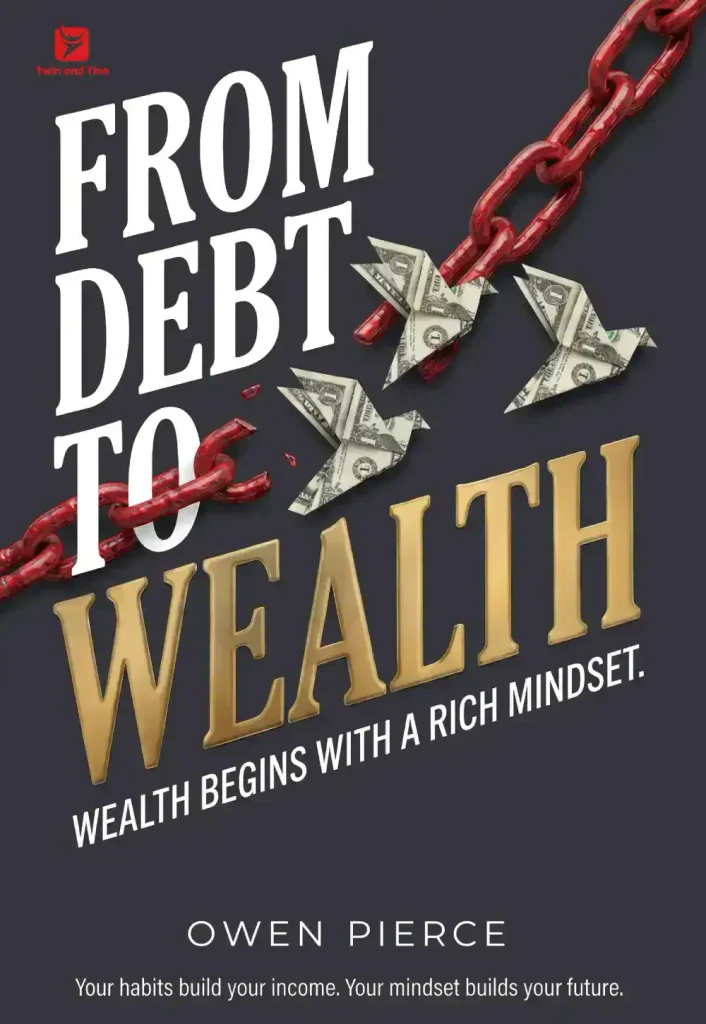
One book I read, From Debt to Wealth by Owen Pierce, made a point that stayed with me. Wealth is not about how much you earn. It is about how you structure, keep, and grow what you have. That sentence annoyed me at first. It felt like a trick. But the more I sat with it, the more honest it seemed.
The question on the cover is one I could not answer for years. Why do I make money every month and still have nothing left? If that question stings a little, you are probably in the right place.
Think about your own life. When income rises, does savings rise with it? Usually not. Expenses breathe in to fill the space. The cycle does not break because of laziness. It breaks because nobody taught us to see money as a system instead of a monthly event.
What Actually Changes in a Money Mindset?
Here is a question I ask myself now. When I spend money, am I buying an asset or feeding a liability?
A liability takes money out of your pocket every month. A car. A bigger apartment. A subscription you forgot about. An asset puts money back in, or at least holds its value while you sleep.
I am not going to pretend this is easy. For years I thought my apartment was an asset because everyone calls it that. It was not. It cost me every single month. That realization stung.
The mindset shift has three parts, and they build on each other.
- Stop trading time for money as your only plan. A salary is a starting point, not the finish line.
- Pay yourself first. Most of us save whatever is left after spending. There is never anything left. Flip it.
- Let time do the heavy lifting. Small amounts, consistently invested, quietly outgrow big amounts invested late.
These are not complicated ideas. Living them is the hard part.
Does Tracking Your Money Actually Work?
I resisted tracking for years. It felt like homework. But a friend showed me her system, and it was almost embarrassingly simple. She wrote down three numbers every week. What came in. What went out. What she kept.
The third number was the one that changed things. Not income. Not spending. What she kept.
Try this for one month. Just one number, once a week. You might be surprised how quickly your behavior adjusts when you can see the truth in front of you.
Which Debt Should You Pay Off First?
When I finally faced my own debt, I had three balances and no idea where to start. One book suggested tackling the smallest balance first, purely for the momentum. Another said attack the highest interest rate. Both work. The one that works for you is the one you will actually finish.
I chose the smallest. It was not mathematically optimal, but paying it off in six weeks gave me something a spreadsheet could not. Belief that I could do this.
The Three-Number Rule
Here is the framework I have used for two years now. I call it the Three-Number Rule, and it takes about ten minutes every Sunday.
Number one. What came in this week. Total, not net. Just the raw figure.
Number two. What went out. Everything. Rent, groceries, that impulse purchase you would rather forget.
Number three. What stayed. The difference. This is the number that matters.
Write all three on a sticky note or in your phone. At the end of the month, look at the trend. Is Number Three growing? Shrinking? Flat?
The ritual does two things. It removes the guesswork, and it removes the shame. You are not judging yourself. You are just watching a pattern.
What Changes When Two People Manage Money Together?
This deserves its own section because it nearly broke us. Early on, I handled everything and my partner felt shut out. She would ask a question about our savings, and I would get defensive.
What fixed it was not a budget. It was visibility. We each kept our own Three-Number notes, then shared them. No blame. Just information.
If you are managing money with a partner, try this. Separate tracking, shared review. It respects both people’s autonomy while keeping the household honest.
When Should You Start Investing?
The honest answer is boring. Start when you have an emergency cushion and no high-interest debt eating you alive. Not before. Paying twenty percent interest while earning seven percent in the market is a losing game.
Once you are clear, start small. Consistency beats size. A modest amount every month for years will quietly outperform a lump sum you keep waiting to invest at the right time.
FAQ
What is the best book for changing your money mindset?
From Debt to Wealth by Owen Pierce is a good place to start. It focuses on the habits underneath the numbers, not just the math.
Why does my income go up but my savings stay flat?
Because expenses rise to meet income. The fix is not earning more. It is moving savings out first, before spending has a chance to absorb it.
Should I pay off debt or invest first?
Pay off high-interest debt first. If your debt is low, do a little of both. Doing nothing is the worst option.
How do I track money without it feeling like homework?
Use the Three-Number Rule. Three numbers, once a week. What came in, what went out, what stayed. Ten minutes.
When is it too late to start?
It is never too late. Starting today beats starting next year. Consistency matters more than timing.
One Last Thing
That Tuesday evening at the kitchen table, I was not failing. I was just starting to look.
The number on the calculator did not change that night. But the way I saw it did, and that turned out to be the only thing that mattered.
References
- Pierce, Owen. From Debt to Wealth.
- Housel, Morgan. The Psychology of Money. Harriman House.
- Kiyosaki, Robert. Rich Dad Poor Dad. Plata Publishing.